OUR SERVICES / SMSF LOANS
Structure your loan correctly with the help of our experienced online self-managed super fund finance brokers.
SMSF (self-managed super fund) loans can be a stand-alone strategy. However, they should generally be used as just one part of your entire strategy. As SMSF specialist brokers, Blue Fox Finance can walk you through the process and help you make the right decisions at every stage.
As a general guideline, anyone with $150k+ combined ($200k preferred) and who is employed can buy a property in an SMSF. As we’re capped to 80% LVR (90% LVR is available, but expensive), you can multiply your super balance by 4 to get your estimated purchase price eligibility. There are further criteria and affordability, but most people are easily eligible for their first purchase.
For the setup, you’ll need to talk to your accountant or financial planner. We do recommend taking the time to do this properly as SMSFs come with a lot of compliance/rules under the SIS Act.
Currently, selling a property in the pension phase (i.e. after retirement) is fully CGT exempt. So purchasing a property now and selling it after retirement might be Capital Gains Tax-free for the entire time it’s been held. There is a balance transfer cap on moving assets to your pension phase, which is currently $2mil. We recommend seeking advice on this one.
If you need to get funds into an SMSF to increase your deposit and make a purchase, there are a couple of ways for most people in the accumulation phase. Be sure to discuss the best way with your accountant/planner if you’re trying to invest in an SMSF.
The first $30k that goes into your super/SMSF each year is taxed in the fund at only 15%, instead of the individual’s personal income tax rate.
Up to $120k can be put in per financial year. As this is not tax-deductible in your personal name and hence taxed at your personal tax rate, the super fund does not tax it. For most people, this is less effective than using concessional contributions.
You can use your unused concessional cap contributions from the last 5 years if your balance is under $500k. So if you have only been putting in $10k super per year, there’s probably a large chunk of carry-forward contributions that can be put in. This is taxed at 15% in the fund and tax-deductible in your personal name.
You can bring-forward up to 3 years’ worth of non-concessional caps. This means you can bring-forward up to $360k of non-concessional caps to make a lump sum entry into super. This is not taxed in the super fund, but not tax-deductible in your personal name.
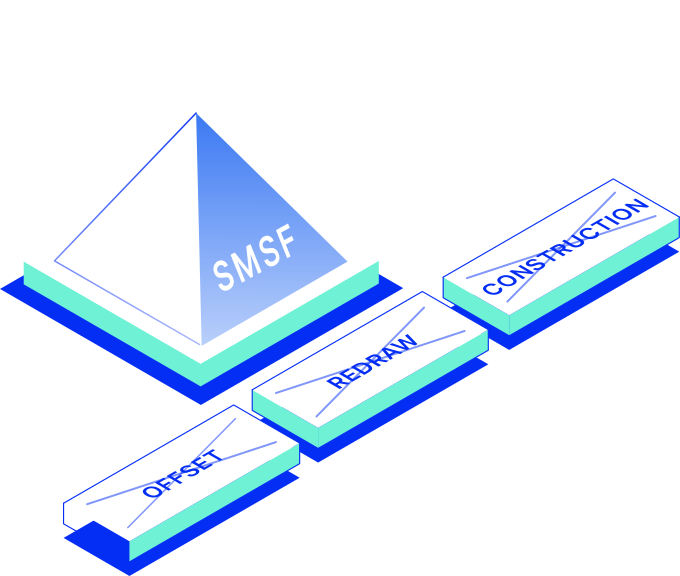
Whilst we do have a lender with an offset account, we generally don’t recommend it. Under the SIS Act, you cannot redraw funds for any purpose other than maintenance or repairs on that property (twice a year). Because self-managed super funds are now funded by non-deposit-taking institutions, they cannot offer a real offset. All their offsets are simply redraws in disguise, hence you may be fined for using an offset incorrectly.
You cannot use equity in an SMSF property for any purpose other than maintenance or repairs of that property, nor can you use it for improvements or other properties or investments.
We don’t offer construction in an SMSF. It is technically possible, but extremely complex.
Unit trusts can be used to purchase using an SMSF and a third party. For example, John’s SMSF can hold 50 units and Jane (personally) can hold 50 units of a unit trust to purchase a commercial property together.
Tripartite agreements are possible where 2 different SMSFs purchase a premise together with separate loan agreements with the lender. For example, when two doctors’ SMSFs purchase 3 medical offices together, they can technically own 1.5 offices each. Should one SMSF default, the other will be given the option to buy out the remaining 1.5 before the security is repossessed.
Generally, SMSFs are funded by non-banks. Banks used to do these often, but had big regulatory issues and were fined for non-compliance. As non-banks get their funding from elsewhere, the rates usually come in about 1% higher than a regular residential or commercial loan.
At Blue Fox Finance, we help you secure a home loan that works with your specific situation. If you’re looking for an experienced finance broker for SMSF loans, reach out to us today. With 9 years of experience and 100+ 5-star reviews from satisfied clients, you can trust us to structure your loan for success.